Business insurance for a moving company protects the business against lawsuits, cargo damage, vehicle accidents, and employee injuries — usually through general liability, cargo, commercial auto, and workers' compensation policies.
This guide is for owners, general managers, and dispatchers of US moving companies. Many movers overpay for the wrong policies or underinsure the risks that actually generate claims. Below we break down every coverage type, the federal and state rules, the real cost drivers, and how to manage claims without drowning in paperwork.
Key Takeaways
| Point | Details |
|---|---|
| Four core policies | Nearly every mover needs general liability, cargo, commercial auto, and workers' compensation coverage as a baseline. |
| Documentation lowers claims | Photo, video, and inventory records at pickup and delivery are the fastest way to shorten disputes and win claim decisions. |
What Is Business Insurance for a Moving Company?
Business insurance for a moving company is a package of policies that shifts the financial risk of accidents, damage, and lawsuits from the business to an insurer. A typical package combines general liability, cargo, commercial auto, and workers' compensation coverage, plus any bonds a state requires.
Moving is a high-contact, high-liability trade. Crews carry heavy furniture through tight doorways, drive box trucks in traffic, and handle a lifetime of a customer's belongings in a single afternoon.
That exposure is why business insurance for moving companies is rarely optional. Clients ask for a certificate of insurance before booking, landlords require one for building access, and federal regulators demand proof before granting authority.
Good movers insurance coverage does three things:
- Pays for third-party injuries and property damage
- Reimburses customers for lost or damaged goods
- Protects the company's own trucks, employees, and cash flow
The Small Business Administration lists property and liability among the standard coverage categories for small businesses — and a moving company touches both at once.
Types of Insurance Every Moving Company Needs
A moving company's core coverage types are general liability, cargo, commercial auto, and workers' compensation. Each closes a different gap.
The table below maps what each policy protects and whether it is legally required.
| Coverage Type | What It Protects | Cost Level | Required or Optional |
|---|---|---|---|
| General liability | Third-party injury and property damage at homes and job sites | Moderate | Required by most clients and landlords |
| Cargo insurance | Customers' goods while in transit or storage | Moderate | Required for interstate movers |
| Commercial auto | Trucks, drivers, and on-road accidents | High | Legally required in every state |
| Workers' compensation | Employee injuries and lost wages | Moderate–High | Required in nearly every state |
| Surety bond | Consumer protection against fraud or non-performance | Low | Confirm the current requirement with your state regulator |
Most movers start with the first four and add the rest as they scale into interstate work or storage. Keeping certificates and renewal dates organized alongside job records is easier when you standardize early — many operators plan for this when choosing their moving company software.
Pro Tip: Ask every carrier for a blanket additional-insured endorsement. Property managers and corporate clients frequently demand to be named on the policy, and adding them one certificate at a time slows down bookings during peak season.
General Liability vs. Cargo Insurance for Movers
The difference is simple: general liability covers damage to other people and their property, while cargo insurance covers the customer's belongings you are moving. Movers confuse them constantly, and that confusion causes denied claims.
Moving company liability insurance — the general liability piece — responds when a crew scratches a doorframe, cracks a tile, or a bystander trips over a dolly. Cargo insurance for movers responds when the customer's dresser is gouged inside the truck or a box of dishes is lost.
Q: Does cargo insurance cover the mover's own truck?
A: No. Cargo insurance covers customers' goods only; the truck itself is covered by commercial auto physical-damage coverage.
Here is how the two policies compare side by side.
| Criteria | General Liability | Cargo Insurance |
|---|---|---|
| What it covers | Injury and damage to third parties and their property | Customer belongings in transit or storage |
| Typical claim | Damaged doorway; injured bystander | Broken furniture; lost boxes; water damage |
| Who requires it | Clients, landlords, venues | FMCSA for interstate household goods movers |
| Covers the items being moved? | No | Yes |
Both matter, and neither replaces the other. General liability for movers is what wins you corporate accounts and building access; cargo protection is what keeps a single damaged antique from wiping out a month's margin.
The cheapest way to control cargo claims is documentation. A short video walkthrough and a photo log of high-value items at pickup and delivery turn a he-said-she-said dispute into a factual record — the same principle behind a good virtual pre-move survey.
Workers' Compensation and Commercial Auto Coverage
Two policies carry the heaviest financial risk in moving: workers' compensation for injured crew and commercial auto for vehicle accidents. Both scale with your headcount and fleet.
Workers compensation moving company operators buy covers medical bills, rehabilitation, and lost wages when an employee is hurt on the job. Moving is physically brutal, which is exactly why premiums run high in this trade.
On the road, the commercial auto insurance movers carry covers trucks, trailers, drivers, and accident liability. A single at-fault highway collision can generate claims far larger than any cargo loss.
Key factors that push these two premiums up:
- Number of trucks and total mileage driven
- Driver motor-vehicle records and CDL status
- Interstate versus local-only operation
- Claims history over the past three to five years
- Crew size and payroll for workers' comp
Keeping experienced movers on staff pays off in service quality.
Pro Tip: Run motor-vehicle-record checks on drivers annually, not just at hire. Insurers reprice on renewal, and one driver with a fresh violation can raise the rate on your entire fleet — catching it early lets you reassign routes before the audit.
Federal and State Insurance Requirements for Movers
Interstate movers must file proof of insurance with the FMCSA, while local movers follow state licensing and insurance rules. Both layers apply if you cross state lines.
Business insurance for moving company compliance starts with the federal minimums. The FMCSA requires for-hire household goods movers to carry at least $750,000 in public liability (bodily injury and property damage) coverage for vehicles of 10,001 lbs GVWR or more, and $300,000 for lighter vehicles. Cargo insurance of $5,000 per vehicle and $10,000 per occurrence is required on top of that.
USDOT insurance requirements are proven through specific filings your insurer submits electronically.
Q: What FMCSA forms do interstate movers file for insurance?
A: Confirm the current filing requirements directly with the FMCSA.
Moving business insurance requirements at the state level add another layer. Many states require a state operating license, and several require a moving company bond — a surety bond that gives consumers a path to relief if the company commits fraud or fails to perform.
Movers must also explain valuation, not just insurance. Valuation is the mover's liability level for the goods, and it is separate from the cargo policy itself.
Pro Tip: Never let a customer sign for Released Value without a signed acknowledgment. Because reimbursement is calculated per pound per article, a television can reimburse only a small fraction of what it cost — customers who are surprised by that amount after a loss file complaints and chargebacks, and a clear signature protects you.
Need help with this? Get started
Moving Company Insurance Cost: What Drives Your Premium
Moving company insurance cost is less about a single price tag and more about the risk profile of the business. A one-truck local operation and a ten-truck interstate carrier can differ by an order of magnitude.
Expect the cost of a full moving-company program — liability, cargo, auto, and workers' comp combined — to climb steeply with fleet size.
Q: What raises a moving company's insurance premium the most?
A: Fleet size, driver records, claims history, and interstate operation are the four biggest cost drivers, with commercial auto typically the largest single line item.
The main variables that move your premium:
- Fleet size and vehicle value — more trucks, higher auto premiums
- Payroll and crew count — the base for workers' compensation
- Operating radius — interstate work triggers federal filings and higher limits
- Claims history — a clean three-year record earns better rates
- Storage operations — warehousing adds property and cargo exposure
The cheapest lever most owners ignore is loss prevention. Tighter dispatch, better labeling, and cleaner damage documentation reduce claim frequency, and fewer claims mean lower renewals — which is why running a tighter moving operation shows up directly in insurance costs. It also protects margin, the same way disciplined pricing strategies for moving companies do.
Choosing the Right Insurance Provider
The right provider specializes in trucking and moving risk, files FMCSA paperwork for you, and handles claims quickly. Generic small-business insurers often misunderstand cargo, valuation, and motor-carrier rules.
Before signing, verify the insurer's financial stability and licensing. Confirming a company's license status and complaint record through state regulators is a five-minute check that prevents a very bad claim-day surprise.
Questions worth asking every candidate:
- Do you file BMC-91 and BMC-34 with the FMCSA directly?
- How are cargo claims valued — replacement cost or actual cash value?
- What is the average claim turnaround time?
- Are additional-insured endorsements included or extra?
- Does the workers' comp rate reflect a safety program discount?
Keep quotes comparable by holding limits and deductibles constant across bids. A cheaper premium with a weaker cargo definition is not cheaper after one denied claim. If you evaluate insurers the way you would evaluate any vendor, the process mirrors how to choose business management software: match the tool to the actual workflow, not the sticker price.
How CRM Software Streamlines Insurance and Claims
A moving CRM reduces insurance friction by keeping damage documentation, signed paperwork, and claim evidence tied to each job in one system. When the underwriting audit or a customer dispute arrives, the evidence is already organized.
The expensive part of a claim is rarely the payout — it is the disorganized scramble for proof. A connected moving company technology stack ties each job to its inventory, its signed paperwork, and its photos, so a disputed scratch is settled with a timestamped record instead of a phone argument.
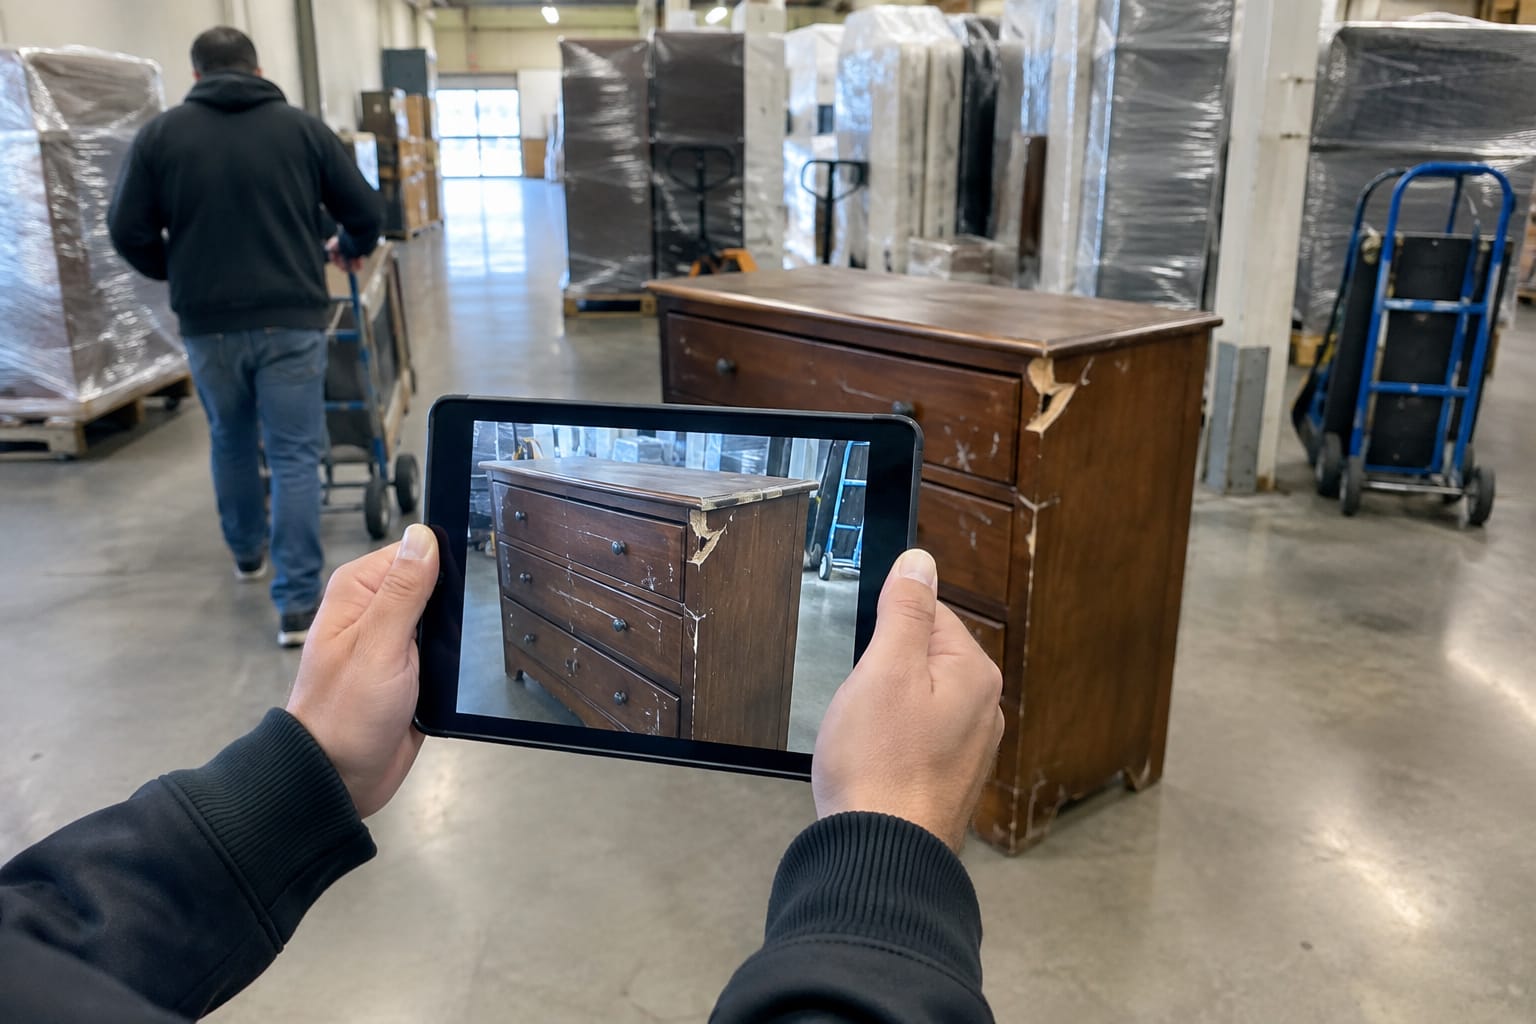
This is where structured moving company CRM operations pay off. Job-level records mean dispatchers, drivers, and office staff work from the same file, and dedicated claims management for movers keeps before/after photos, the signed Bill of Lading, and the inventory on record with a tamper-evident trail — so a claim is a file rather than an argument.
Three workflows that directly cut insurance headaches:
- Damage documentation — before/after photos tied to the exact job, captured on-site in the crew app
- Signed Bill of Lading — e-signed on any screen with timestamps and geolocation, inventory pulled from the estimate with no re-entry
- Tamper-evident claim trail — the signed paperwork and inventory stay on record for every job
The teams that pair strong coverage with disciplined records — a documented inventory, a digital bill of lading and documentation, and a clean claims trail — spend less time fighting disputes and more time booking jobs. If you are still comparing platforms, start with the best CRM for moving companies and evaluate its claims and documentation features first.
Want to see how Virtual Estimate handles claims documentation for your crews? Every plan starts with 14 days free, with no contracts and no cancellation fees — get started here or call (888) 611-7483.
Related Articles
- Employee Retention Strategies for Moving Companies — Understand how experienced crews reduce turnover cost.
- CRM for Moving Companies: Streamline Operations — Find out how a CRM ties jobs, documentation, and claims into one system.
Ready to see it in action?
Book a free 60-minute demo and explore how Virtual Estimate can help your business.